Gold Loan with Low CIBIL Score: Rates & RBI Rules 2026
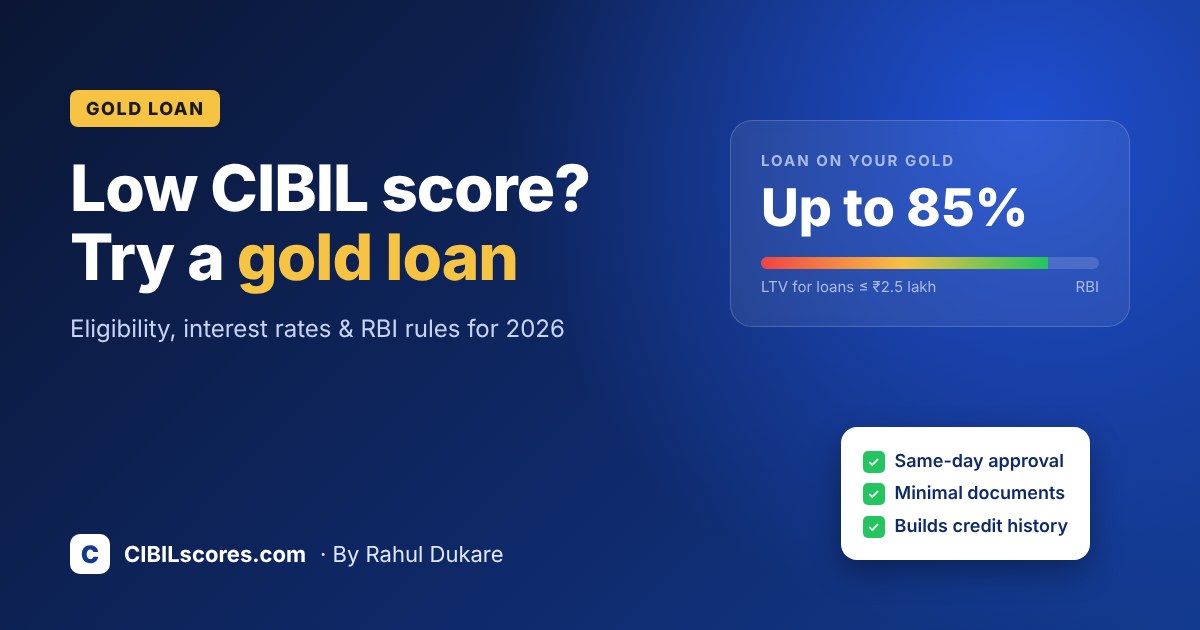
If your CIBIL score is low and banks keep turning down your personal loan application, a gold loan is often the fastest and cheapest way to borrow. Because the loan is backed by your gold, lenders care far less about your credit history. This guide explains how a gold loan works with a low CIBIL score, the RBI rules that apply in 2026, what interest you can expect, and how to use the loan to rebuild your score instead of hurting it.
Can you get a gold loan with a low CIBIL score?
Yes. A gold loan is a secured loan: you pledge gold jewellery or coins, and the lender holds them until you repay. If you do not repay, the lender can auction the gold to recover its money. That security is why most lenders approve gold loans even when your score is below 650, or when you have no credit history at all (NH/NA).
RBI has also said that lenders do not need a detailed creditworthiness appraisal for small gold loans of up to ₹2.5 lakh. In practice, many banks and NBFCs still pull your credit report, but a low score rarely leads to a rejection for a small gold loan. It may, however, affect the interest rate you are offered.
Gold loan vs personal loan when your score is low
| Feature | Gold loan | Personal loan |
|---|---|---|
| Collateral | Gold jewellery or coins | None |
| Approval with score below 650 | Usually approved | Often rejected |
| Typical interest rate | About 8%–18% a year | About 11%–30%+ a year for low scores |
| Processing time | Same day, often within hours | 1–7 days |
| Documents | KYC (Aadhaar, PAN), address proof | KYC, salary slips, bank statements, ITR |
| Risk if you don't repay | Gold is auctioned | Heavy late fees, collection calls, score damage |
If you own gold and need money for a short period, a gold loan is usually cheaper and easier than a personal loan when your score is low. If you need a large amount for many years, a gold loan's 12-month bullet structure may not suit you (see below).
RBI gold loan rules in 2026: what borrowers should know
RBI issued new directions on lending against gold in June 2025, and several of them now apply to every bank and NBFC. The ones that matter most to you:
- Loan-to-value (LTV) limits depend on loan size. You can borrow up to 85% of your gold's value for loans up to ₹2.5 lakh, up to 80% for loans between ₹2.5 lakh and ₹5 lakh, and up to 75% for loans above ₹5 lakh.
- No detailed credit appraisal for small loans. For loans up to ₹2.5 lakh, RBI has said lenders do not need a detailed income or creditworthiness check. This is the main reason gold loans work for people with low scores.
- Bullet loans must be repaid within 12 months. In a bullet loan you pay principal and interest together at the end. The rules no longer allow endless interest-only renewals where the principal keeps rolling over.
- Your gold must be returned quickly. After you fully repay, the lender must return your gold within 7 working days. If it delays, it must pay you ₹5,000 for each day of delay.
- Transparent valuation. Gold must be valued at a market-linked price, and you have the right to be present during valuation.
- Quantity limits. You can pledge up to 1 kg of gold jewellery and up to 50 grams of gold coins per borrower.
Rules can be updated, so always confirm the current terms in your loan agreement and on the lender's official website.
How much can you borrow? A quick example
Suppose you pledge 40 grams of 22-carat jewellery and the lender values your gold at ₹2,80,000 (lenders value only the pure gold content, not making charges or stones).
- If you borrow up to ₹2.5 lakh, the maximum LTV is 85%, so you could get up to about ₹2,38,000.
- The actual amount may be a little lower, because lenders deduct for stones, wax and purity.
Borrow only what you need. A smaller loan is easier to repay on time, and on-time repayment is what helps your CIBIL score.
Gold loan interest rates in 2026
Rates change often, especially after RBI changes the repo rate. As a rough guide in 2026:
| Lender type | Typical interest rate (per year) |
|---|---|
| Public sector banks (e.g. SBI, Canara Bank) | About 8%–11% |
| Private banks | About 9%–14% |
| Gold loan NBFCs (e.g. Muthoot, Manappuram, IIFL) | About 10%–18% or higher, depending on the scheme |
Banks are usually cheaper, while NBFCs are often faster and more flexible. With a low CIBIL score, some lenders may put you in a higher-rate scheme, so compare at least three offers. Also check processing fees, valuation charges and penalties for late payment.
Documents required
Most lenders ask for very little:
- Aadhaar card and PAN card
- Address proof (if different from Aadhaar)
- Passport-size photograph
- The gold you want to pledge
Income proof is usually not needed for small gold loans.
How to apply for a gold loan with a low CIBIL score
- Check your CIBIL report first. Look for errors such as loans you never took or wrong late payments. Fixing errors can improve your offers on every loan, not just this one.
- Compare lenders. Check the interest rate, LTV offered, processing fee and repayment options at a bank and at least two NBFCs.
- Visit the branch or book a doorstep service. Choose only RBI-regulated banks and NBFCs. Be present when your gold is tested and weighed.
- Read the loan agreement. Note the interest rate, tenure, repayment type (EMI, interest-monthly or bullet) and the auction policy if you miss payments.
- Collect your pledge receipt. It should list each item, its weight and purity. Keep it safe; you will need it to get your gold back.
Can a gold loan improve your CIBIL score?
Yes, if you handle it well. Banks and NBFCs report gold loans to credit bureaus like any other loan. Paying every instalment or interest payment on time adds positive history to your report, which slowly lifts a low score.
To make a gold loan work for your score:
- Choose an EMI or monthly-interest option if a single bullet payment would be hard to arrange.
- Set a reminder or auto-debit a few days before each due date.
- Close the loan on time and keep the closure letter.
The opposite is also true. Missing payments on a gold loan is reported as a default and can lower your score further, and the lender may auction your gold. With credit bureaus now receiving updates from lenders several times a month, both good and bad behaviour show up on your report faster than before.
Risks to watch out for
- Auction risk. If you miss payments, the lender can auction your gold after giving notice. Family jewellery can be lost this way.
- Gold price falls. If gold prices drop sharply, the lender may ask you to pay part of the loan or pledge more gold.
- Hidden charges. Ask about valuation fees, renewal fees and penal charges before you sign.
- Unregulated lenders. Avoid local moneylenders or anyone who cannot give a proper receipt and loan agreement.
Better options if you don't own gold
If you do not have gold to pledge, other secured options may help, such as a loan against a fixed deposit or a secured credit card. See our guide to personal loan options for a low CIBIL score for more ideas, and our plan to increase your CIBIL score from 600 to 750 to qualify for cheaper loans in future.
Frequently asked questions
What is the minimum CIBIL score for a gold loan?
There is no fixed minimum. Because the loan is secured by gold, most lenders approve gold loans even with a score below 650 or with no credit history. A higher score may still get you a lower interest rate.
Do lenders check CIBIL for a gold loan?
Many do, but for small gold loans up to ₹2.5 lakh, RBI has said a detailed credit appraisal is not required. The check is mainly used to set your rate and confirm your identity.
How much gold loan can I get on 10 grams of gold?
It depends on the gold's purity and the lender's gold rate. Under RBI rules, for loans up to ₹2.5 lakh you can get up to 85% of the value of the pure gold content. Lenders publish their per-gram loan rate daily, so check it on the day you apply.
Will a gold loan improve my CIBIL score?
Yes. Gold loans are reported to credit bureaus. Paying on time builds positive history and can help raise a low score over a few months.
What happens if I can't repay my gold loan?
The lender will first send reminders and a notice. If you still do not pay, it can auction your gold to recover the dues, and the missed payments will be reported to credit bureaus. Talk to your lender early if you expect trouble; you may be able to pay part of the loan or restructure it.
This article is for general information only and is not financial advice. Interest rates and rules change, so check the latest terms with your lender before borrowing.